Loading...
By Philip Herold| April 2026 | Latin America Energy & Infrastructure
In March 2026, Brazil closed what is, by any measure, the largest single energy auction in its history. The LRCap — Leilão de Reserva de Capacidade — contracted approximately 19 GW of generation capacity and mobilized an estimated R$ 65 billion (roughly USD 12–13 billion) in committed investment. The headline numbers generated the predictable round of congratulatory coverage: Brazil is open for business, the energy transition pipeline is real, and institutional capital is following. Then Brazil's Tribunal de Contas da União opened a post-award review of the auction, and the story got considerably more complicated.[1]
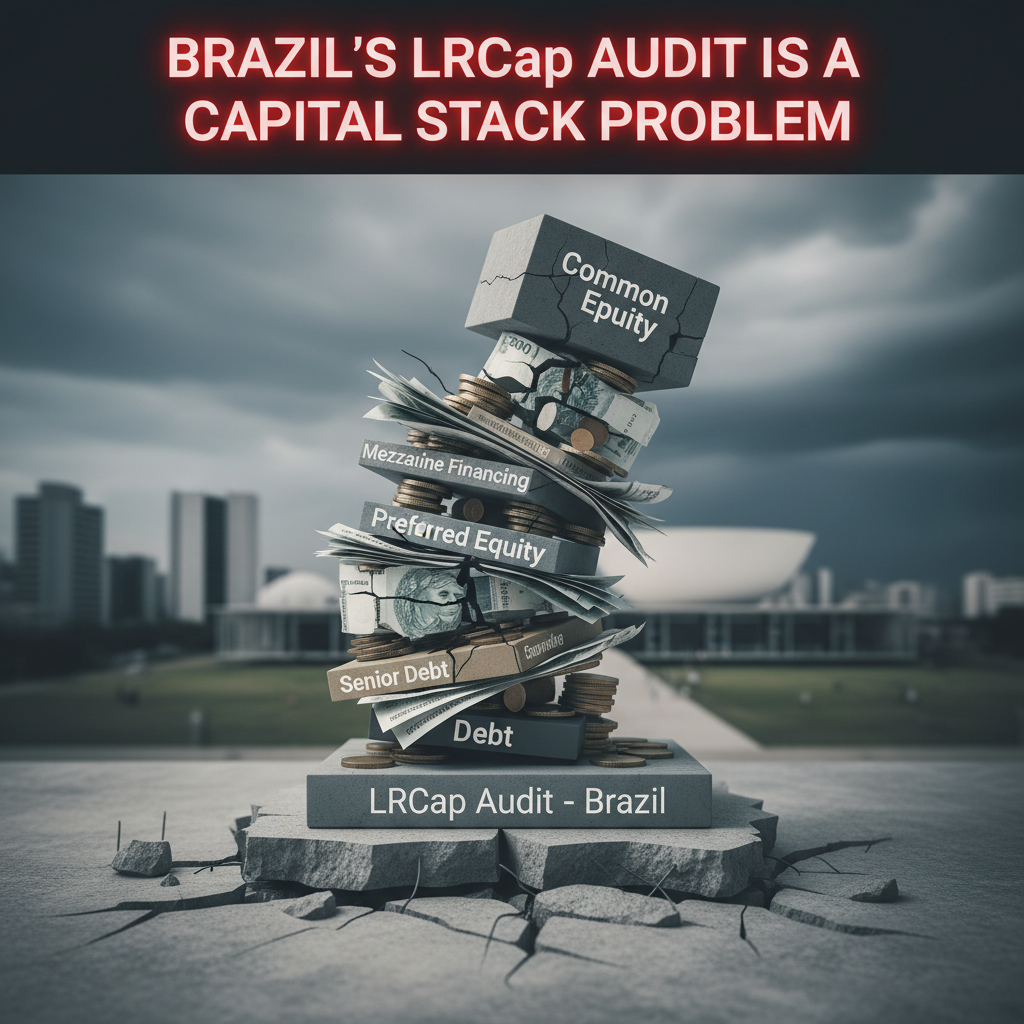
The instinct among many market participants has been to frame this as a regulatory speed bump — an audit process that will eventually clear, after which normal project finance timelines resume. That framing is wrong, and it is wrong in ways that matter specifically to lenders who are currently modeling financial close. The TCU's intervention is not a reputational or political risk. It is a structural attack on the enforceability of the offtake contract — and the offtake contract is the primary debt-service mechanism in every project finance structure in this portfolio.
What the TCU Can Actually Do — and Why the Grounds Matter
The TCU is not a court in the conventional sense, but it holds powers that most project finance practitioners outside Brazil underestimate. It can suspend, modify, or void federal government contracts. It can freeze disbursements from BNDES — Brazil's national development bank, which historically provides 70–80% of debt financing for auction-contracted generation projects at subsidized TJLP-linked rates. And critically, it can do all of this while a contract is already signed and parties are in active financial close discussions.
What the TCU has not yet done — at least not in any public filing available as of this writing — is specify the precise grounds for its review with the granularity that lenders need. This is the single most important analytical gap in the market right now. The grounds determine everything about scope. If the TCU's concern is a procedural irregularity in the bidding process — a deficient notice period, a disqualified bidder, a scoring methodology that was applied inconsistently — the risk may be narrow and correctable. A procedural defect might affect a subset of awarded contracts, or might be cured through a directed renegotiation with affected parties. That is an uncomfortable but manageable scenario for most capital stacks.
If, however, the TCU's concern goes to pricing methodology — specifically, whether the capacity payments were set at levels that constitute an unlawful transfer to generators at ratepayer expense — the risk is systemic. A pricing challenge affects every contract in the portfolio simultaneously and cannot be remedied by procedural correction. It requires either a renegotiation of the core economic terms or a judicial contest that could take years to resolve. The Mexico 2021 analogue is instructive here: when AMLO's energy reform retroactively altered renewable auction contracts, Enel, Iberdrola, and others ultimately pursued ICSID arbitration under USMCA — not because they wanted to litigate, but because the alternative was accepting a rewritten economics on projects already under construction.
Brazil's TCU review is a different legal mechanism than Mexico's legislative override — but it produces an identical problem for project lenders: an offtake contract whose enforceability cannot be cleanly represented in a financing opinion.
The BNDES Freeze Scenario and Commercial Debt Bridge Costs
Assume, for modeling purposes, that the TCU issues a precautionary suspension while its review proceeds. The immediate mechanical consequence is not project cancellation — it is a BNDES disbursement freeze. Developers who have structured their capital stacks around 70–80% BNDES debt at TJLP-linked rates now face a binary choice: bridge with commercial debt or seek standstill agreements with their existing lenders.
Commercial bridge debt for investment-grade sponsors in the current Brazilian market is priced at roughly CDI + 250–350 basis points. For projects sized in the R$ 2–4 billion range — which describes the larger solar and wind portfolios in the LRCap pool — the annualized carry cost of bridging BNDES with commercial debt is material enough to breach debt-service coverage ratio covenants in a significant number of term sheets. Developers who signed contracts in March assuming Q2–Q3 2026 financial close are now running out of room on their bridge timelines.
The ANEEL transmission auction scheduled for October 2026 — which includes a R$ 1.3 billion project currently under consideration for inclusion — offers a useful counterpoint.[2] Transmission concessions carry a structurally different revenue guarantee mechanism and have not been implicated in the TCU review. Sophisticated capital that was considering the generation layer may quietly reweight toward transmission over the next two quarters. This is not a retreat from Brazil; it is a flight to the less legally encumbered segment of the same market.
The Procedural Timeline Is the Most Important Variable No One Is Tracking
TCU reviews do not operate on a fixed schedule. Historical precedent runs the full range: some reviews resolve within 30 days when the government agency under review files a compelling defense and the TCU's rapporteur finds the challenge unsubstantiated. Others — the Belo Monte hydropower concession being the most cited example — produced injunctions that delayed financial close by 12–36 months and ultimately required renegotiated contract terms before BNDES would resume disbursements.
The critical procedural question that remains unanswered in public filings is whether ANEEL and the Ministry of Mines and Energy have filed, or intend to file, a formal defense of the auction terms with the TCU. This is not a formality. A well-constructed agency defense — particularly one that addresses the specific grounds of the TCU's concern with supporting documentation — can materially accelerate resolution and signal to lenders that the government is prepared to stand behind the contracts it awarded. The absence of a public defense posture, or a delayed response, sends the opposite signal and will be interpreted by risk committees as an indicator that the underlying concern has merit.
TotalEnergies CEO Patrick Pouyanné's announced withdrawal from three additional offshore wind markets in April 2026 is a reminder that major international sponsors are actively repricing sovereign and regulatory risk across jurisdictions.[3] Brazil does not need to become Mexico 2021 to lose competitive access to capital — it only needs to become the market where the risk-adjusted return no longer clears the hurdle rate for allocators who have other options.
What to Watch: The Dockets and Milestones That Matter
For lenders and sponsors with exposure to LRCap contracts, the near-term monitoring list is specific. First: the TCU's formal statement of grounds, which should accompany or shortly follow the opening of the review process. The specificity of that document — procedural versus substantive; narrow versus portfolio-wide — is the primary risk-sorting signal. Second: any public filing by ANEEL or MME constituting a defense of the auction terms, and the timeline on which the TCU's rapporteur is expected to respond. Third: whether any awarded developers proactively seek declaratory relief in Brazilian federal courts to establish contract enforceability independent of the TCU process — a strategy that has been used in prior concession disputes to create parallel legal protection while the audit proceeds.
The SmartestEnergy acquisition of a majority stake in Factor Energia — announced April 21 and targeting the retail and procurement layer of the Iberian and LatAm energy market — is a useful data point for context.[4] Sophisticated market entrants are currently distinguishing sharply between the generation project layer, which carries the TCU risk, and the trading and retail layer, which does not. That bifurcation is rational. It also tells you something about where institutional conviction in the Brazilian energy market actually sits right now.
The 19 GW contracted under LRCap represents a genuine infrastructure buildout that Brazil needs and that private capital wants to finance. The TCU review does not change that underlying reality. What it does is insert a period of enforceability uncertainty into the critical window between contract award and financial close — and in project finance, that window is where deals either happen or quietly die.
References
- "SmartestEnergy Enters Iberia and Latin America Through the Acquisition of a Majority Stake in Factor Energia, S.A." Brave: Latin America Power & Energy / Marubeni News Release, 21 April 2026. https://www.marubeni.com/en/news/2026/release/00018.html
- "TotalEnergies CEO Pouyanne rules out three more offshore wind markets after US exit." Upstream Online, 20 April 2026. https://www.upstreamonline.com/energy-transition/totalenergies-ceo-pouyanne-rules-out-three-more-offshore-wind-markets-after-us-exit/2-1-1976984
- "Total boss rules out three more offshore wind markets after US exit." Recharge News, 20 April 2026. https://www.rechargenews.com/offshore-wind/total-boss-rules-out-three-more-offshore-wind-markets-after-us-exit/2-1-1976731
- "Maior leilão de energia do país enfrenta incertezas." Valor Econômico, 19 April 2026. https://valor.globo.com/empresas/noticia/2026/04/18/maior-leilao-de-energia-do-pais-enfrenta-incertezas.ghtml
- "Aneel analisa incluir projeto de R$ 1,3 bilhão em leilão de transmissão de outubro." ePowerBay / Brave: Brazil Energy Markets, 18 April 2026. https://www.epowerbay.com/single-post/aneel-analisa-incluir-projeto-de-r-1-3-bilhao-em-leilao-de-transmissao-de-outubro